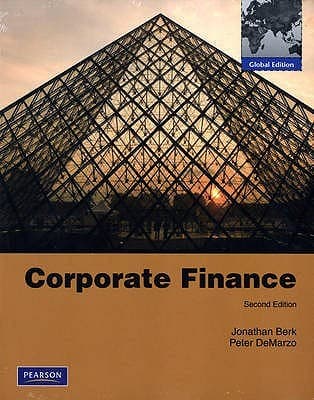
Core Idea
- Difficulty
- Hard
- Read it if
- You are a student or professional seeking a rigorous, comprehensive, and theoretically sound introduction to corporate finance principles, valuation, and financial decision-making, with a strong emphasis on foundational economic concepts.
- Skip it if
- You are looking for a quick, high-level overview or an introductory book with minimal quantitative analysis. This book is a deep dive, not a light read.
Key Takeaways from Corporate Finance
The Law of One Price: Your Financial North Star
Identical assets must trade at identical prices in efficient markets.
The Law of One Price (LOOP) is the main idea in corporate finance, providing a consistent way to value things. It says that if two assets or portfolios have the same cash flows and risks, they must sell for the same price, no matter how they were created. This removes arbitrage opportunities and means financial decisions are about present value calculations. LOOP helps value complex financial tools by breaking them into simpler parts. It ensures that a firm's investment decisions focus on getting the most present value from future cash flows, instead of looking for 'bargains' that don't exist in efficient markets. Understanding LOOP helps make good capital budgeting, financing, and dividend policy decisions.
“In competitive markets, the Law of One Price states that if equivalent investment opportunities trade simultaneously in different markets, they must trade for the same price in both markets.”
In the book: The book consistently uses the LOOP to derive and explain various valuation models, such as the valuation of a bond by replicating its cash flows with a portfolio of zero-coupon bonds, or valuing a stock using the dividend discount model, implicitly assuming that the stock's future cash flows could be replicated by an equivalent portfolio if one existed.
Try this: Always evaluate investment opportunities by asking: 'What would it cost to replicate the exact same cash flow stream and risk profile elsewhere?' If the cost is lower than the asset's price, it's overvalued; if higher, it's undervalued. This thinking forces a present value perspective and eliminates emotional biases.
Related ideas: arbitrage, present-value, efficient-market-hypothesis
Separation Principle: Value Creation, Unburdened
Investment decisions should be independent of financing decisions.
The Separation Principle is a key idea in corporate finance. It says that in perfect capital markets, a firm's investment decisions (capital budgeting) can be judged separately from its financing decisions (how it gets money). This is because any financial transaction, like issuing debt or equity, has a zero-NPV in a perfect market. A project creates value by generating cash flows that are more than its costs, not by how it is funded. Managers should first find projects with positive Net Present Value (NPV). Then, separately, they should decide on the best capital structure to fund these projects. This principle simplifies decision-making by letting managers focus on the operational and strategic value of investments without getting distracted by financing details.
“The Separation Principle states that security transactions in a perfect capital market neither create nor destroy value. Thus, the value of the firm is independent of its financing choices.”
In the book: The book illustrates this by showing how the NPV rule for project selection holds regardless of whether the project is funded by debt or equity, assuming no market imperfections like taxes or bankruptcy costs. The value of the firm is the sum of the present values of its projects, not the sum of its financing sources.
Try this: When evaluating a new project, calculate its NPV based purely on its expected cash flows and appropriate discount rate, without considering how it will be financed. Only after determining its viability should you consider the optimal mix of debt and equity to fund it.
Related ideas: npv, capital-budgeting, capital-structure
Net Present Value: The Gold Standard for Decision Making
Maximizing firm value means accepting all projects with a positive NPV.
The Net Present Value (NPV) rule is the most reliable way to make capital budgeting decisions because it directly measures how much a firm's value changes. By bringing all future cash flows of a project back to the present and subtracting the initial investment, NPV shows exactly how much value a project adds to the firm. A positive NPV means the project is expected to create more value than it costs. This makes it a good investment that will increase shareholder wealth. Unlike other measures, NPV considers the time value of money and the project's size, giving a clear rule for maximizing value. Using the NPV rule helps a company consistently take on projects that increase value.
“The Net Present Value (NPV) of a project is the difference between the present value of its benefits and the present value of its costs. When making an investment decision, the NPV rule states that you should accept any project with a positive NPV.”
In the book: The book uses numerous examples of capital budgeting scenarios where projects are evaluated using NPV. For instance, comparing two mutually exclusive projects, the one with the higher positive NPV is chosen, even if another metric like IRR might suggest otherwise, because NPV directly measures wealth creation.
Try this: Always prioritize calculating the NPV for any potential investment. Be meticulous in estimating cash flows and choosing the appropriate discount rate. If NPV > 0, the project adds value; if NPV < 0, it destroys value. Don't be swayed by high IRRs if the NPV is low or negative, especially for projects with differing scales or cash flow patterns.
Related ideas: discount-rate, cash-flow, time-value-of-money
Risk and Return: The Inseparable Duo
Higher expected returns are a compensation for bearing higher risk.
The main idea of finance is the balance between risk and return. Investors are rational and dislike risk, meaning they will only take on more risk if they expect a higher return. This relationship is shown through ideas like the Capital Asset Pricing Model (CAPM). This model shows how an asset's expected return depends on the risk-free rate, the market risk premium, and the asset's systematic risk (beta). Understanding this is important for investors choosing portfolios and companies evaluating projects. Firms must make sure that the expected returns from their investments pay enough for the systematic risk they add, matching shareholder expectations and the cost of capital.
“The expected return of an investment is the return an investor expects to earn on average. Risk is a measure of the uncertainty of returns. Investors demand a risk premium for bearing risk.”
In the book: The book presents historical data showing how different asset classes (e.g., T-bills, bonds, stocks) have delivered varying average returns corresponding to their historical volatility and risk. It then introduces CAPM to formalize this relationship, using beta as the measure of systematic risk.
Try this: When evaluating an investment, always assess its inherent risk. For corporate projects, this means understanding the project's beta and using it to determine the appropriate discount rate (cost of capital). For personal investing, ensure your portfolio's expected return is commensurate with the level of risk you are comfortable bearing, and diversify to minimize unsystematic risk.
Related ideas: capm, beta, systematic-risk, risk-premium
Efficient Markets: Information is Power (and Price)
Prices reflect all available information, making 'beating the market' difficult.
The Efficient Market Hypothesis (EMH) says that in a truly efficient market, asset prices quickly and fully show all public information. This means investors cannot consistently make extra returns using past prices (weak form efficiency), public information (semi-strong form efficiency), or even private information (strong form efficiency). While strong form efficiency is often debated, semi-strong efficiency suggests that analyzing public data is unlikely to consistently lead to better performance. For company managers, EMH means that trying to 'trick' the market is pointless; the market will quickly price in the true economic value of decisions. It reinforces the need to focus on real value creation rather than speculative trading.
“An efficient market is a market in which security prices reflect all available information. In such a market, it is impossible to consistently earn an excess return.”
In the book: The book discusses various studies, such as event studies, that show how stock prices react almost immediately to news announcements (e.g., earnings reports, mergers). It also points to the difficulty of active fund managers consistently outperforming passive index funds over long periods.
Try this: As a corporate manager, focus on making sound, value-enhancing operational and investment decisions, as the market will eventually recognize and price this value. As an investor, consider passive investing strategies (e.g., index funds) as a practical approach, acknowledging the difficulty of consistently outperforming a truly efficient market.
Related ideas: emh, arbitrage, information-asymmetry, passive-investing
Capital Structure: Finding the Optimal Debt-Equity Mix
Leverage can enhance returns but also magnify risk.
A firm's capital structure—the mix of debt and equity it uses—is an important decision that affects its cost of capital and total value. While the Modigliani-Miller (MM) ideas suggest that in perfect markets, capital structure doesn't matter, real-world issues like taxes, financial distress costs, and agency costs make it very important. Debt offers a tax shield, as interest payments are tax-deductible, which can lower a firm's weighted average cost of capital (WACC). However, too much debt increases the chance of financial trouble and bankruptcy, raising the cost of equity and debt. Finding the best capital structure means balancing the benefits of debt's tax shield against the rising costs of financial trouble. The goal is to minimize WACC and maximize firm value.
“A firm's capital structure refers to the relative proportions of debt, equity, and other securities that it uses to finance its assets.”
In the book: The book details the MM propositions, then systematically introduces market imperfections. It shows how the tax deductibility of interest creates a benefit to debt, but then explains how increasing debt also increases the probability and cost of financial distress, leading to a U-shaped WACC curve and an optimal capital structure.
Try this: Analyze your company's current debt-to-equity ratio in light of industry averages, tax rates, and its business risk. Consider increasing debt if your firm has stable cash flows and is underleveraged to capture tax benefits. However, be cautious not to exceed a level where financial distress costs outweigh these benefits, which could trigger credit rating downgrades or higher borrowing costs.
Related ideas: wacc, modigliani-miller, financial-distress, tax-shield
Payout Policy: Returning Value to Shareholders
Dividends and share repurchases are two ways to distribute earnings.
A firm's payout policy decides how it gives extra cash back to shareholders. The two main ways are dividends and share repurchases. In perfect capital markets, Modigliani and Miller say that payout policy doesn't matter, as shareholders can create their own 'homemade dividends.' But in reality, things like taxes, agency costs, and signaling effects make payout policy important. Dividends give a regular income but can be less tax-efficient for some investors. Share repurchases offer flexibility, can signal that a company is undervalued, and are often more tax-efficient. The best policy balances these factors, aiming to maximize shareholder wealth by returning capital efficiently while keeping enough for future good investments. Firms must consider their investment chances, financial flexibility, and shareholder preferences.
“A firm's payout policy is the way a firm chooses to return capital to its shareholders. The two main mechanisms are dividends and share repurchases.”
In the book: The book discusses the 'dividend puzzle' and then explains how share repurchases have become increasingly popular due to their tax advantages and flexibility. It cites studies showing how dividend initiations or large share repurchase announcements can signal positive information to the market.
Try this: As a company, regularly review your cash flow generation and investment opportunities. If internal projects with positive NPV are scarce, consider returning capital to shareholders. Choose between dividends and repurchases based on the tax implications for your shareholder base, the need for flexibility, and the signaling effect you wish to convey to the market.
Related ideas: dividends, share-repurchase, agency-costs, signaling-theory
Valuation Methods: Beyond Simple Discounting
Different contexts require different valuation approaches, all rooted in LOOP.
While the Law of One Price provides the theory, practical valuation uses different methods. The Dividend Discount Model (DDM) values equity based on expected future dividends. The Free Cash Flow to Equity (FCFE) and Free Cash Flow to Firm (FCFF) models value equity or the whole firm by discounting the cash available to equity holders or all capital providers. Multiples-based valuation (e.g., P/E, EV/EBITDA) uses similar companies to estimate value, assuming similar firms should have similar valuations. Each method has good and bad points, and the choice depends on the company's traits, industry, and data availability. All these methods try to apply the Law of One Price by estimating the present value of future cash flows or by finding similar assets.
“While the Law of One Price is the fundamental principle, there are several methods to implement it in practice, depending on the information available and the specific asset being valued.”
In the book: The book dedicates chapters to each valuation method, providing detailed calculations and examples for DDM, FCFF/FCFE, and comparable company analysis. It highlights situations where one method might be more appropriate than another, such as using FCFF for firms that don't pay dividends or multiples for private companies.
Try this: When valuing a company or project, don't rely on just one method. Use multiple approaches (e.g., DCF and multiples) to triangulate a valuation range. Understand the assumptions and limitations of each method and be prepared to justify your choice based on the specific context of the valuation.
Related ideas: dcf, ddm, multiples-valuation, free-cash-flow
Real Options: Flexibility Has Value
Managerial flexibility adds value to projects beyond static NPV.
Standard NPV analysis often assumes a fixed plan, but managers can actually change decisions based on future events. These 'real options'—like the option to expand a project if it works, stop it if it fails, or delay it until more information is available—add value to a project that static NPV calculations might miss. Recognizing and valuing these options, often using option pricing models, gives a clearer picture of a project's true worth. Ignoring real options can lead to not investing enough in projects with high strategic value or high uncertainty, because the value of flexibility isn't included. Including real options encourages a more flexible approach to capital budgeting.
“A real option is the right, but not the obligation, to take a particular business action, such as deferring, expanding, abandoning, or staging a project.”
In the book: The book discusses examples such as the option to abandon a failing project (a put option), the option to expand production if demand is high (a call option), or the option to defer an investment until market conditions are clearer. It may use simplified Black-Scholes calculations to illustrate their value.
Try this: When performing capital budgeting, identify and quantify any embedded real options within a project. Don't just rely on a single, static NPV. Consider how managerial flexibility could enhance value under different future scenarios. This will lead to better strategic decisions and potentially justify projects that appear marginal under a static analysis.
Related ideas: option-pricing, black-scholes, strategic-options, uncertainty
Agency Problems: Aligning Incentives
Conflicting interests between managers and shareholders can destroy value.
Agency problems are common in corporate finance. They happen because ownership (shareholders) and control (managers) are separate. Managers, as agents, might not always act in the best interest of shareholders (the principals). This can lead to decisions that prioritize personal gain, perks, or building a bigger company over increasing shareholder wealth. These conflicts can be reduced through things like good corporate governance (e.g., independent boards), incentive pay (e.g., stock options, performance bonuses), and the threat of hostile takeovers. Understanding agency costs helps design good corporate structures and pay schemes that align manager incentives with creating shareholder value, ensuring firms run well and ethically.
“Agency problems arise when managers, despite being hired as agents of shareholders, pursue their own interests rather than maximizing shareholder wealth.”
In the book: The book discusses examples like managers investing in negative NPV projects to expand their division, excessive executive compensation not tied to performance, or managers resisting value-enhancing takeovers. It then outlines governance solutions such as linking executive pay to stock performance or independent board oversight.
Try this: As a board member or senior executive, critically evaluate compensation structures to ensure they genuinely incentivize long-term shareholder value creation, not just short-term gains or personal benefits. Implement robust governance mechanisms, including independent oversight, to monitor managerial actions and mitigate potential conflicts of interest.
Related ideas: corporate-governance, executive-compensation, shareholder-value, takeovers
Corporate Finance Quotes
“The goal of financial management is to maximize the current value per share of the existing stock.”
“The value of any investment opportunity is the present value of the cash flows it will generate in the future.”
“Agency costs are the costs that arise from conflicts of interest between managers and shareholders.”
“The efficient markets hypothesis states that security prices reflect all available information.”
“The cost of capital is the minimum return a project must earn to increase firm value.”
“Leverage magnifies both gains and losses, increasing the risk and potential return of equity.”
“Dividend policy is irrelevant in a perfect capital market, as investors can create their own dividend streams.”
“Systematic risk cannot be diversified away and is compensated by the market risk premium.”
“Real options add value to projects by providing flexibility to adapt to future uncertainties.”
“The trade-off theory of capital structure balances the tax benefits of debt against the costs of financial distress.”
“Working capital management involves balancing profitability and liquidity in short-term assets and liabilities.”
“Mergers and acquisitions can create value through synergies, but often fail due to overpayment or integration issues.”
“The pecking order theory suggests firms prefer internal financing, then debt, and equity as a last resort.”
Quiz
10 questions on the main ideas. Each answer comes with a short explanation.
Question 1
What is the central unifying valuation framework used throughout Berk and DeMarzo's 'Corporate Finance'?
- Capital Asset Pricing Model (CAPM)
- Discounted Cash Flow (DCF) Analysis
- Law of One Price
- Modigliani-Miller Theorem
Show answer
C. Law of One Price The book explicitly states it uses the Law of One Price as a unifying valuation framework to present corporate finance concepts consistently.
Question 2
Which version of Berk and DeMarzo's book is specifically tailored for a one-semester corporate finance course?
- Corporate Finance (31 chapters)
- Corporate Finance: The Core
- Fundamentals of Corporate Finance
- Advanced Corporate Finance
Show answer
B. Corporate Finance: The Core The description specifies that 'Corporate Finance: The Core' is streamlined for first one-semester courses, while the 31-chapter version is for longer sequences.
Question 3
According to the book's description, what three elements does it aim to provide to readers?
- Theory, practice, and case studies
- Core content, new ideas, and effective pedagogy
- Quantitative models, qualitative analysis, and ethics
- Historical context, current trends, and future predictions
Show answer
B. Core content, new ideas, and effective pedagogy The book description states it presents 'the core content readers expect, the new ideas they want, and the pedagogy they need to succeed.'
Question 4
For which academic scenario is the 31-chapter 'Corporate Finance' book by Berk and DeMarzo recommended?
- A one-semester introductory course
- A two-semester or longer sequence
- A short executive education program
- A self-study reference only
Show answer
B. A two-semester or longer sequence The description clarifies that the 31-chapter book is for programs using a two-semester or more sequence, contrasting with the streamlined 'Core' version.
Question 5
How does the Law of One Price framework help in teaching corporate finance according to the book?
- By focusing exclusively on market efficiency theories
- By providing a consistent method to value different financial decisions
- By simplifying all calculations to basic arithmetic
- By emphasizing historical stock price data
Show answer
B. By providing a consistent method to value different financial decisions The Law of One Price serves as a unifying framework that applies to various corporate finance topics, ensuring valuation consistency across chapters.
Question 6
What is a key pedagogical feature implied by the book's description?
- It includes extensive real-world case studies from Fortune 500 companies
- It is designed to help students succeed through effective teaching methods
- It relies heavily on advanced mathematical derivations
- It prioritizes international finance over domestic topics
Show answer
B. It is designed to help students succeed through effective teaching methods The description mentions providing 'the pedagogy they need to succeed,' indicating a focus on teaching methods that aid student learning.
Question 7
Which of the following best describes the target audience for 'Corporate Finance: The Core'?
- MBA students in advanced finance electives
- Undergraduates or graduates in their first corporate finance course
- Practicing CFOs seeking continuing education
- Researchers specializing in financial economics
Show answer
B. Undergraduates or graduates in their first corporate finance course The book is tailored for the first one-semester course, making it suitable for introductory-level students in undergraduate or graduate programs.
Question 8
In the context of this book, what might 'new ideas' refer to based on the description?
- Cutting-edge financial technologies like blockchain
- Recent developments and innovations in corporate finance theory
- Brand new mathematical models invented by the authors
- Ideas from unrelated fields like psychology or sociology
Show answer
B. Recent developments and innovations in corporate finance theory The phrase 'new ideas they want' suggests inclusion of contemporary concepts and updates in the field, beyond just traditional core content.
Question 9
How does the book's structure likely differ between 'Corporate Finance: The Core' and the 31-chapter version?
- The Core version omits advanced topics to focus on essentials for a shorter course
- The Core version includes more case studies but fewer theoretical chapters
- The 31-chapter version is abridged with fewer examples
- Both versions have identical content but different publishers
Show answer
A. The Core version omits advanced topics to focus on essentials for a shorter course Since 'The Core' is streamlined for one semester, it likely covers fundamental topics concisely, while the full version expands on these with additional chapters.
Question 10
What is a practical implication of using the Law of One Price framework as taught in this book?
- It allows investors to always beat the market through arbitrage
- It provides a basis for valuing securities and making corporate financial decisions consistently
- It guarantees that all assets will have the same price in different markets
- It eliminates the need for risk assessment in capital budgeting
Show answer
B. It provides a basis for valuing securities and making corporate financial decisions consistently The Law of One Price is applied to ensure that valuation methods are coherent across topics like capital budgeting, capital structure, and valuation, aiding practical decision-making.
Corporate Finance FAQ
What is the Law of One Price in corporate finance?
The Law of One Price is a unifying valuation framework used throughout the book, stating that identical assets must have the same price in efficient markets. It provides a consistent approach to valuing financial decisions, linking core concepts like net present value and risk.
How is 'Corporate Finance: The Core' different from the full 'Corporate Finance' textbook?
'Corporate Finance: The Core' is a streamlined version specifically designed for one-semester courses, covering essential topics in a focused manner. The full 'Corporate Finance' textbook has 31 chapters and is intended for two-semester or more comprehensive sequences.
Does the book cover practical valuation techniques?
Yes, the book emphasizes practical valuation techniques using the Law of One Price framework. It includes real-world applications, examples, and problem sets to help readers apply concepts like discounted cash flow analysis and capital budgeting in corporate settings.
What are the key topics covered in 'Corporate Finance: The Core'?
Key topics include time value of money, valuation of stocks and bonds, capital budgeting, risk and return, cost of capital, capital structure, and payout policy. It focuses on core principles needed for a foundational understanding of corporate finance.
How does this book compare to other corporate finance textbooks like Brealey and Myers?
This book distinguishes itself by using the Law of One Price as a central unifying framework, offering a consistent approach to valuation. While Brealey and Myers also cover similar topics, Berk and DeMarzo's emphasis on this framework provides a structured pedagogy for learning.
Is this book suitable for beginners in finance?
Yes, it is designed for first-course students, with clear explanations, pedagogical tools, and a focus on core concepts. It assumes no prior finance knowledge, making it accessible for undergraduates or professionals new to the field.
Does the book include case studies or real-world examples?
Yes, it incorporates real-world examples, case studies, and practical applications to illustrate concepts like corporate valuation and financial decision-making. This helps bridge theory with practice in business contexts.
What is the role of pedagogy in this book?
Pedagogy is central, with features like learning objectives, summaries, problem sets, and integrated examples to reinforce understanding. It is tailored to support student success in grasping complex finance concepts effectively.
Can this book be used for self-study?
Yes, its structured approach, clear explanations, and practical exercises make it suitable for self-study. Individuals seeking to learn corporate finance fundamentals can use it independently, though instructor resources may enhance learning.
How does the book address modern corporate finance issues?
It covers contemporary topics within its core framework, such as risk management and capital structure decisions, using current examples and applications. The Law of One Price framework allows it to adapt to evolving financial practices.
Similar books
- Steve Jobs
Walter Isaacson
4.1 (957k) average on GoodreadsBusinessSteve Jobs was a visionary who fused creativity and technology to revolutionize six industries and shape our digital world.
- Freakonomics: A Rogue Economist Explores the Hidden Side of Everything
Steven D. Levitt
4.0 (709k) average on GoodreadsBusinessThis book uses economic principles to reveal the surprising incentives behind everything from drug dealing and real estate to cheating teachers and the decline of crime.
- The Tipping Point: How Little Things Can Make a Big Difference
Malcolm Gladwell
4.0 (690k) average on GoodreadsBusinessMalcolm Gladwell explains how small, targeted actions can start widespread changes in trends, behaviors, and ideas.
- Outliers: The Story of Success
Malcolm Gladwell
4.2 (556k) average on GoodreadsBusinessMalcolm Gladwell argues that true success is not just about individual talent, but about the hidden advantages of culture, opportunity, and unique experiences that shape extraordinary lives.
- The Subtle Art of Not Giving a F*ck: A Counterintuitive Approach to Living a Good Life
Mark Manson
3.9 (530k) average on GoodreadsBusinessEmbrace your flaws and stomach life's lemons, because true happiness isn't about relentless positivity, but about choosing what truly matters to give a f*ck about.
- The 7 Habits of Highly Effective People: Powerful Lessons in Personal Change
Stephen R. Covey
4.1 (524k) average on GoodreadsBusinessThis book presents seven habits that help people live more effective, purposeful lives.



Enjoyed the summary?
A summary gives you the shape of the book. The book itself has the detail, the examples and the voice.
Find Corporate Finance on AmazonAs an Amazon Associate, BookBrief earns from qualifying purchases. How we're funded