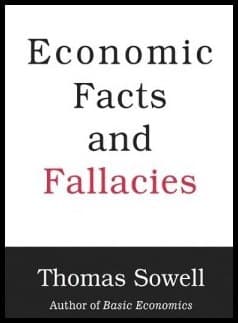
Core Idea
- Difficulty
- Medium
- Read it if
- You want to sharpen your critical thinking about economic and social policies, understand common logical pitfalls in public discourse, and see how empirical data often contradicts popular narratives. It's ideal for those seeking a conservative perspective on economic analysis.
- Skip it if
- You are looking for a detailed introduction to economic theory, prefer a more progressive or interventionist economic viewpoint, or find Sowell's direct and often critical tone challenging.
Key Takeaways from Economic Facts and Fallacies
The Zero-Sum Fallacy
Wealth creation is often misunderstood as merely redistribution, ignoring productivity.
Sowell often disproves the zero-sum fallacy, the idea that one person's gain must come at another's expense. This thinking often supports policies aimed at 'redistributing' wealth or income, instead of creating conditions for its growth. He argues that economic activity, especially in a free market, is mostly about increasing overall societal wealth through innovation, efficiency, and trade, where both sides often benefit. For example, when a company becomes more profitable, it often means it is providing more value to consumers, creating jobs, and investing in new projects, rather than simply taking from others. Understanding this difference is key to moving beyond politics driven by envy and toward policies that encourage real economic growth and prosperity for everyone.
“Many economic policies are based on the fallacy that wealth is a fixed pie to be divided, rather than something that can be created.”
In the book: Sowell frequently references historical examples of market economies generating unprecedented wealth, contrasting them with centrally planned economies where the focus on redistribution led to stagnation. He might cite the post-WWII economic boom in Western nations driven by production and trade, as opposed to the Soviet Union's command economy.
Try this: When evaluating economic policies or business decisions, ask whether the proposed action aims to create new value or merely reallocate existing resources. Prioritize solutions that expand the 'pie' rather than just re-slicing it. Support policies that incentivize productivity, innovation, and voluntary exchange.
Related ideas: zero-sum-fallacy, wealth-creation, economic-growth, market-efficiency
The 'Snapshot' vs. 'Process' Fallacy
Income disparities are often misconstrued by ignoring individual mobility over time.
A major fallacy Sowell discusses is the misinterpretation of income statistics. Critics often point to single 'snapshots' of income distribution, showing large differences between income groups at one time, and conclude there is systemic inequality or lack of opportunity. Sowell argues this ignores the dynamic 'process' of economic life: individuals and households often move between income groups over their lifetimes. A young person starting their career might be in a lower group, while the same person later, with more experience and skills, moves to a higher one. This mobility, rather than fixed class structures, is common in many market economies, making simple comparisons of 'rich' versus 'poor' at one moment very misleading about long-term trends and individual paths.
“Many statistics on income distribution are like a snapshot of a parade, showing different people at different stages, rather than the same people moving through those stages.”
In the book: Sowell cites studies from the University of Michigan and the U.S. Treasury Department showing that a significant percentage of individuals in the lowest income quintile move to higher quintiles within a decade, and many in the highest quintile fall to lower ones. He also mentions how age and lifecycle stages heavily influence income, with peak earning years typically in middle age.
Try this: When analyzing income data, always seek longitudinal studies that track individuals or households over time, not just cross-sectional data. Recognize that income differences often reflect life-cycle stages, skill acquisition, and personal choices rather than immutable class divisions. Focus on policies that enhance upward mobility and skill development, rather than just redistributing current income.
Related ideas: income-mobility, income-inequality, longitudinal-data, economic-opportunity
The Fallacy of Intent vs. Effect
Well-intentioned policies often have counterproductive and unseen consequences.
Sowell consistently highlights the important difference between a policy's stated intentions and its actual, often unintended, effects. Many economic fallacies come from judging policies only by their good goals without carefully analyzing their real-world results. He argues that politicians and activists often prioritize the appearance of 'doing something' over understanding the complex, often negative, results of their actions. Minimum wage laws, rent control, and occupational licensing are clear examples where the stated goal (helping the poor, making housing affordable, ensuring quality) often leads to job losses, housing shortages, and reduced competition. A clear economic analysis must always look past the rhetoric to the incentives created and the consequences, both visible and hidden.
“The road to hell is paved with good intentions, especially in economics, where the actual consequences often diverge sharply from the desired ones.”
In the book: Sowell extensively discusses rent control policies, illustrating how they lead to housing shortages, deterioration of existing units, and black markets, despite the stated aim of making housing more affordable. He also critiques minimum wage laws for reducing employment opportunities for low-skilled workers.
Try this: Before supporting any new policy, always ask: 'What are the likely *unintended* consequences of this action?' and 'Who might be negatively affected, even if not directly targeted?' Prioritize policies that align incentives with desired outcomes, rather than relying solely on good intentions. Demand data on actual results, not just promises.
Related ideas: unintended-consequences, policy-analysis, incentives, economic-effects
The Fallacy of Composition
What is true for an individual is not necessarily true for the group.
Sowell identifies the fallacy of composition as a common error in economic thinking: assuming that what is true or good for one part must also be true or good for the whole. This fallacy often supports misguided government interventions. For example, while saving money is smart for an individual, widespread, simultaneous saving during an economic downturn can make a recession worse (Keynes' paradox of thrift). Similarly, an individual firm might benefit from higher prices, but if all firms in an industry raise prices at once, demand might drop for everyone. Understanding that group behavior can produce different outcomes than individual actions is crucial for avoiding overly simple policy ideas that do not account for systemic interactions.
“What makes sense for one individual to do, such as standing up in a crowd to see better, can become self-defeating if everyone does it.”
In the book: Sowell often uses the example of tariffs: while a specific domestic industry might benefit from protection against foreign competition, widespread tariffs across many industries typically lead to higher prices for consumers, reduced overall trade, and retaliatory tariffs, ultimately harming the national economy.
Try this: When considering a policy or economic argument, always ask if the reasoning holds when scaled up to the entire population or economy. Be wary of solutions that seem intuitively correct for a single entity but might break down when universally applied. Look for systemic effects and feedback loops.
Related ideas: fallacy-of-composition, aggregate-demand, macroeconomics, systemic-thinking
The 'Experts' Fallacy and Knowledge Problem
Centralized planning by 'experts' is inherently limited by dispersed, localized knowledge.
Sowell, like Hayek, criticizes the 'experts' fallacy: the belief that a select group of intellectuals or government planners can effectively manage complex economies. He argues that economic knowledge is not held in one place but is spread among millions of individuals, each with unique, local, and often unspoken information about their preferences, skills, and opportunities. Market prices, through supply and demand, act as important signals that combine this dispersed knowledge, allowing for efficient resource allocation without central direction. Attempts by 'experts' to override these signals, whether through price controls, industrial policy, or other forms of central planning, always lead to inefficiencies, shortages, and misallocations because they lack the necessary, constantly changing information that only a decentralized system can process.
“The fatal conceit is to believe that a small group of central planners can possess and process the vast, dispersed knowledge of an entire society more effectively than the decentralized mechanisms of the market.”
In the book: Sowell frequently contrasts the economic performance of market economies with centrally planned ones (e.g., Soviet Union, Cuba), highlighting the chronic shortages, poor quality, and lack of innovation in the latter due to the inability of planners to manage vast amounts of information.
Try this: Be skeptical of claims that a small group of 'experts' can effectively plan or micromanage an entire economy or industry. Advocate for policies that empower decentralized decision-making and allow market prices to signal information. Recognize that individuals, not central planners, are best positioned to make decisions about their own economic lives.
Related ideas: knowledge-problem, central-planning, market-efficiency, hayek
The Demographic Fallacy
Economic disparities between groups often reflect age, geography, and culture, not inherent discrimination.
Sowell systematically addresses the assumption that all economic differences between different groups (e.g., racial, ethnic, gender) are mainly due to discrimination. He points out that such differences often strongly relate to variations in age distribution, geographic location, education level, work experience, and cultural factors that influence skills and career choices. For example, groups with a younger average age will, on average, have lower incomes due to less work experience. Similarly, groups living in regions with fewer economic opportunities will earn less. Confusing these underlying, non-discriminatory factors with systemic prejudice leads to misguided policies that fail to address the actual causes of disparity and can even worsen them by focusing on symptoms rather than the real drivers of economic outcomes.
“Many economic disparities attributed to invidious discrimination can be largely, if not entirely, explained by demographic differences in age, location, and cultural factors affecting human capital.”
In the book: Sowell provides extensive data showing that when controlling for age, education, and hours worked, many racial and gender income gaps shrink significantly or even disappear. He points to immigrant groups who, despite facing initial prejudice, achieve economic success over generations by accumulating human capital and adapting to new economic environments.
Try this: When encountering statistics on group disparities, always inquire about confounding variables such as age, education, geographic location, and family structure. Avoid immediate assumptions of discrimination as the sole or primary cause. Focus on policies that enhance human capital development and economic opportunity for all individuals, regardless of group identity.
Related ideas: demographic-disparities, discrimination, human-capital, income-gaps
The Fallacy of Causation vs. Correlation
Observing two things together doesn't mean one causes the other.
A repeated idea in Sowell's analysis is the important difference between correlation and causation. He argues that many economic fallacies come from observing two things happening together (correlation) and mistakenly concluding that one directly causes the other. For instance, an increase in social spending might correlate with a reduction in poverty, but this does not automatically mean the spending caused the reduction; other factors could be involved, or the causation could even be reversed (less poverty leading to more social spending). This logical error leads to ineffective or even harmful policy decisions, as it misidentifies the true drivers of economic outcomes. Careful economic analysis requires identifying the actual causal mechanisms, often needing controlled studies or careful historical comparison, rather than just superficial connections.
“Correlation is not causation, a fundamental truth often ignored when people seek simple explanations for complex social phenomena.”
In the book: Sowell often discusses the correlation between minimum wage increases and poverty rates. While proponents argue minimum wage reduces poverty, he points out that many minimum wage earners are not poor (e.g., teenagers from middle-class families) and that minimum wage increases can lead to job losses, which *increase* poverty for those affected. He also cites examples where increased spending on certain programs did not lead to the desired outcomes.
Try this: When presented with data showing two trends moving together, always ask: 'Is there a direct causal link, or could there be a third variable influencing both?' or 'Could the causation run in the opposite direction?' Demand evidence of causal mechanisms, not just statistical associations. Avoid drawing hasty conclusions from simple correlations.
Related ideas: causation-correlation, statistical-fallacies, economic-reasoning, critical-thinking
The Urban Planning Fallacy
Top-down urban policies often ignore market signals and the organic evolution of cities.
Sowell pays close attention to fallacies surrounding urban problems, arguing that many well-intentioned city planning efforts and housing policies are deeply flawed. He criticizes the tendency to see cities as static things to be designed from above, rather than dynamic, changing places shaped by millions of individual decisions and market forces. Rent control, for example, is a classic urban fallacy that, despite aiming to make housing affordable, always leads to housing shortages and decay. Similarly, strict zoning laws and 'smart growth' plans, while appearing progressive, often drive up housing costs and limit economic mobility by preventing natural market responses to demand. Sowell supports policies that allow cities to respond naturally to economic signals, promoting real affordability and dynamism.
“Urban problems are often exacerbated by policies based on abstract theories rather than on the concrete realities and incentives faced by people in cities.”
In the book: Sowell repeatedly uses the example of rent control in cities like New York and San Francisco, detailing how it leads to landlords withdrawing properties from the market, neglecting maintenance, and discouraging new construction, ultimately harming the very tenants it purports to help. He also discusses how restrictive zoning increases housing costs.
Try this: When evaluating urban policies, consider the incentives they create for residents, developers, and businesses. Be wary of top-down mandates that ignore market signals. Advocate for policies that promote flexibility, allow for organic growth, and remove artificial barriers to housing supply and economic activity.
Related ideas: urban-planning, rent-control, zoning-laws, market-signals
The 'Compassion' Fallacy
Emotional appeals often bypass rational analysis of economic policy effectiveness.
Sowell often highlights the 'compassion' fallacy, where a policy's appeal relies almost entirely on its stated good intentions, often presented with moral urgency, while avoiding careful economic analysis of its actual results. This fallacy is particularly dangerous because it frames any opposition to the policy as a lack of compassion or empathy, effectively stopping rational debate. Sowell argues that true compassion in policy-making requires a clear assessment of what actually works to reduce suffering and improve lives, not just what sounds good or feels right. Many policies enacted out of a desire for compassion, such as minimum wage increases or price controls, often harm the very people they intend to help, making an objective analysis of consequences essential.
“Compassion is a noble human trait, but when it becomes the sole criterion for economic policy, it can lead to devastating consequences because emotion is no substitute for analysis.”
In the book: Sowell often refers to various welfare programs or 'anti-poverty' initiatives that, despite massive spending and good intentions, have failed to significantly reduce poverty or have created long-term dependency, as seen in some inner-city communities in the US.
Try this: When evaluating policies, separate the emotional appeal from the economic analysis. Always demand evidence of effectiveness and consider potential negative consequences, even for policies presented as 'compassionate.' Prioritize solutions that empower individuals and create sustainable opportunities, rather than those that merely offer symbolic gestures.
Related ideas: compassion-fallacy, policy-effectiveness, emotional-reasoning, rational-analysis
The 'Solution' vs. 'Trade-off' Fallacy
Most economic decisions involve trade-offs, not perfect solutions without costs.
Sowell consistently reminds readers that economics is about allocating scarce resources, meaning almost every decision involves trade-offs. The 'solution' fallacy arises when politicians or commentators present policies as perfect cures to problems, without any costs or negative consequences. This ignores opportunity cost – the value of the next best alternative given up. For example, spending more on healthcare means less money for education or infrastructure. Imposing environmental regulations might improve air quality but could increase production costs and consumer prices. Sowell emphasizes that understanding economics means acknowledging these trade-offs, openly discussing the costs and benefits of different approaches, and making informed choices, rather than seeking mythical 'solutions' that promise everything to everyone without sacrifice.
“There are no solutions, only trade-offs. This fundamental reality is ignored by those who promise to solve complex problems without acknowledging the costs and sacrifices involved.”
In the book: Sowell frequently discusses environmental regulations, showing how they impose costs on industries and consumers, even while providing benefits. He also points to government spending programs where the 'solution' to one problem (e.g., unemployment benefits) comes with the 'trade-off' of reduced work incentives or increased taxes.
Try this: When presented with any policy proposal, always ask: 'What are the trade-offs involved?' and 'What are we giving up by choosing this option?' Be wary of anyone promising 'solutions' without acknowledging costs. Demand a clear articulation of both benefits and opportunity costs.
Related ideas: trade-offs, opportunity-cost, scarcity, economic-decision-making
Economic Facts and Fallacies Quotes
“The first lesson of economics is scarcity: There is never enough of anything to satisfy all those who want it. The first lesson of politics is to disregard the first lesson of economics.”
“Many economic policies are justified on the basis of what things are 'worth' -- rather than on how much it costs to produce them or what price they will fetch in a free market.”
“The real minimum wage is zero. That is the wage that many workers receive when minimum wage laws price them out of jobs.”
“Much of the social history of the Western world over the past three decades has been a history of replacing what worked with what sounded good.”
“It is amazing how many people think that they can improve the world by simply saying that things should be better.”
“Prices are not just a way of transferring money. They are a way of transferring information.”
“People who talk about the need for 'balance' in the media usually mean that they want the media to be biased in their direction.”
“The next time some politician, pundit, or professor tells you that the rich are not paying their 'fair share' of taxes, ask them what that 'fair share' is, and how they arrived at that particular figure.”
“The great tragedy of the modern welfare state is that it has created a moral hazard by subsidizing irresponsibility.”
“Much of the 'knowledge' dispensed in our schools and colleges today consists of opinions and emotions rather than facts and logic.”
“It is hard to imagine a more stupid or more dangerous way of making decisions than by putting those decisions in the hands of people who pay no price for being wrong.”
“Many of the 'solutions' to our problems are simply ways of transferring the costs of those problems to others.”
“Competition is not just a matter of who wins and who loses. It is a matter of who gets to try.”
“Facts do not speak for themselves. They must be interpreted by theories or assumptions.”
Quiz
10 questions on the main ideas. Each answer comes with a short explanation.
Question 1
According to Sowell, what is a primary reason economic fallacies persist and have 'staying power'?
- They are always promoted by powerful corporations.
- They often possess a certain plausibility that makes them seem reasonable.
- Most people lack any formal education in economics.
- They are inherently simple and easy to understand.
Show answer
B. They often possess a certain plausibility that makes them seem reasonable. Sowell emphasizes that fallacies are not just crazy ideas but have a 'certain plausibility' which contributes to their staying power, making careful examination of their flaws necessary.
Question 2
Which of the following topics is explicitly mentioned in the book's description as an area where Sowell exposes economic fallacies?
- The economics of space exploration.
- Mistaken ideas about urban problems.
- The impact of social media on economic behavior.
- The history of mercantilism.
Show answer
B. Mistaken ideas about urban problems. The book description specifically lists 'mistaken ideas about urban problems' as one of the areas where Sowell dissects economic fallacies.
Question 3
Sowell states that the book is written in a style similar to his previous work, 'Basic Economics.' What does this imply about the target audience or required background knowledge?
- It requires advanced degrees in economics.
- It is intended for professional economists only.
- It does not require any prior knowledge of economics by the reader.
- It is written for students currently enrolled in economics Ph.D. programs.
Show answer
C. It does not require any prior knowledge of economics by the reader. The description explicitly states that the book 'does so in a lively manner and without requiring any prior knowledge of economics by the reader,' consistent with the style of 'Basic Economics'.
Question 4
When discussing 'income differences,' what is Sowell likely to argue is often overlooked or misrepresented in popular discourse?
- The primary cause is always technological innovation.
- The role of individual choices, age, experience, and productivity differences.
- That income differences are solely due to government policy.
- That income differences are a myth.
Show answer
B. The role of individual choices, age, experience, and productivity differences. Consistent with Sowell's broader work, when addressing 'income differences,' he typically highlights factors like age, experience, education, work ethic, and individual choices, arguing that simplistic explanations often ignore these crucial elements.
Question 5
The book mentions 'male-female economic differences.' Based on Sowell's general approach, what kind of fallacy might he address in this context?
- The fallacy that all economic differences between genders are solely due to innate biological differences.
- The fallacy that all observed economic differences are exclusively due to discrimination, ignoring other voluntary choices or market factors.
- The fallacy that there are no economic differences between genders.
- The fallacy that women are inherently better at economics than men.
Show answer
B. The fallacy that all observed economic differences are exclusively due to discrimination, ignoring other voluntary choices or market factors. Sowell often challenges explanations that attribute all disparities solely to discrimination, instead exploring how factors like career choices, hours worked, risk aversion, and time spent in the labor force can contribute to observed economic differences, thereby exposing fallacies that ignore these complexities.
Question 6
How does 'Economic Facts and Fallacies' differ from 'Basic Economics' in its approach, according to the description?
- 'Economic Facts and Fallacies' is a much shorter, introductory text.
- This latest book is able to go into greater depth, with real world examples, on specific issues.
- 'Economic Facts and Fallacies' requires a strong background in advanced mathematics.
- It focuses exclusively on historical economic theories rather than contemporary issues.
Show answer
B. This latest book is able to go into greater depth, with real world examples, on specific issues. The description states, 'Written in the easy-to-follow style of the author's Basic Economics, this latest book is able to go into greater depth, with real world examples, on specific issues.'
Question 7
Regarding 'Third World countries,' what common economic fallacy might Sowell likely challenge?
- The idea that these countries' poverty is primarily due to a lack of natural resources.
- The assumption that their economic problems are solely caused by exploitation from developed nations, ignoring internal policies and institutions.
- The belief that all 'Third World countries' are economically identical.
- The notion that foreign aid is always detrimental.
Show answer
B. The assumption that their economic problems are solely caused by exploitation from developed nations, ignoring internal policies and institutions. Sowell frequently critiques explanations that externalize all blame for a nation's economic woes, often highlighting the critical role of domestic policies, cultural factors, and institutional frameworks in economic development, thus challenging fallacies of external causation.
Question 8
Given Sowell's focus on 'economic facts and fallacies,' what is a likely implication for how readers should approach information from 'the media and by politicians'?
- Assume all information from these sources is inherently false.
- Accept all widely disseminated beliefs as truths without question.
- Critically examine the underlying assumptions and evidence for claims, especially those that are widely accepted.
- Trust only sources that explicitly agree with Sowell's conclusions.
Show answer
C. Critically examine the underlying assumptions and evidence for claims, especially those that are widely accepted. The book's premise is to expose fallacies 'widely disseminated in the media and by politicians,' implying that readers should adopt a critical, evidence-based approach to such information rather than passive acceptance or blanket rejection.
Question 9
Sowell often uses 'real-world examples' to debunk fallacies. What does this suggest about his methodology compared to purely theoretical economic arguments?
- He prioritizes abstract mathematical models over empirical observations.
- He believes economic theory is irrelevant without practical application and historical context.
- He exclusively uses fictional scenarios to illustrate points.
- He avoids any form of data analysis.
Show answer
B. He believes economic theory is irrelevant without practical application and historical context. Sowell's emphasis on 'real-world examples' demonstrates his commitment to empirical evidence and historical context to test and often refute theoretical claims or popular misconceptions, arguing that economic principles must be grounded in observable reality.
Question 10
The book's description mentions that examining the flaws of fallacies can sometimes be 'humorous.' What does this suggest about Sowell's tone or the nature of some economic misconceptions?
- That economic fallacies are never serious and should always be laughed at.
- That the logical inconsistencies or absurd real-world consequences of some fallacies can be ironically amusing.
- That Sowell intentionally writes the book as a comedy.
- That humor is used to distract from the lack of rigorous economic analysis.
Show answer
B. That the logical inconsistencies or absurd real-world consequences of some fallacies can be ironically amusing. The 'humorous' aspect likely stems from the often-striking contrast between the plausible-sounding nature of a fallacy and its glaring logical flaws or the absurd outcomes when applied to real-world scenarios, which Sowell often highlights with sharp wit.
Economic Facts and Fallacies FAQ
What is the main purpose of 'Economic Facts and Fallacies'?
'Economic Facts and Fallacies' aims to debunk common misconceptions and popular fallacies surrounding various economic issues. It provides clear, evidence-based arguments to expose the flaws in widely held beliefs often spread by media and politicians, making complex topics accessible to the general reader.
Does 'Economic Facts and Fallacies' require prior knowledge of economics?
No, the book is specifically written to be accessible to readers without any prior background in economics. Thomas Sowell explains complex concepts in a straightforward manner, similar to his acclaimed 'Basic Economics', ensuring a broad audience can understand and engage with the material.
What kind of economic fallacies does the book address?
The book tackles a wide range of fallacies, including mistaken ideas about urban problems, income disparities, economic differences between genders, and issues related to academia, race, and Third World countries. It delves into beliefs that, while plausible, are fundamentally flawed when examined critically.
What is Sowell's perspective on why economic fallacies persist?
Thomas Sowell argues that economic fallacies endure not because they are inherently crazy, but because they possess a certain plausibility that makes them appealing and hard to dislodge. The book emphasizes the importance of carefully examining these flaws, which can often be both necessary and even humorous.
How does 'Economic Facts and Fallacies' differ from 'Basic Economics'?
While both books share Sowell's easy-to-follow style and make economics accessible, 'Economic Facts and Fallacies' goes into greater depth on specific issues and fallacies with real-world examples. 'Basic Economics' provides a broader foundational understanding, whereas this book focuses on dissecting particular misconceptions.
Does the book offer solutions to economic problems?
The primary focus of 'Economic Facts and Fallacies' is to clarify economic realities and expose flawed thinking rather than proposing specific policy solutions. By debunking common fallacies, it aims to provide readers with a clearer understanding of how economies actually work, which can inform better decision-making.
What examples does Sowell use to illustrate economic fallacies?
Sowell employs numerous real-world examples to illustrate economic fallacies, drawing from diverse areas such as urban development, labor markets, educational institutions, and international relations. These examples help to ground abstract economic principles in tangible, relatable scenarios.
Is 'Economic Facts and Fallacies' relevant to current economic discussions?
Absolutely. The fallacies discussed in the book, concerning topics like income inequality, gender pay gaps, and the role of government, remain highly relevant in contemporary economic and political debates. Sowell's insights provide a valuable framework for critically evaluating present-day arguments.
About the author
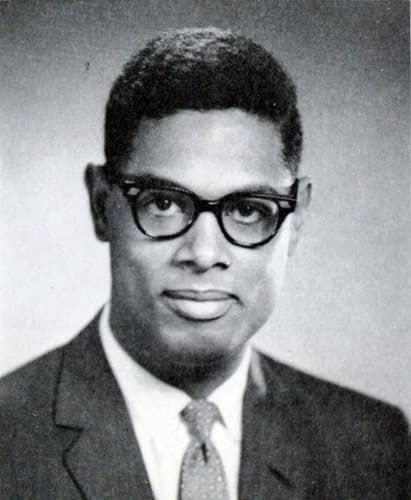
Thomas Sowell is an American economist and political commentator known for his writings on economics, race, and social policy. His notable works include "Black Rednecks and White Liberals," which explores cultural influences on behavior, "Economic Facts and Fallacies," which addresses common misconceptions in economics, "Intellectuals and Society," examining the impact of intellectuals on public policy, and "The Quest for Cosmic Justice," discussing the implications of justice in society.
Similar books
- The Road to Serfdom
Friedrich A. Hayek
4.2 (19k) average on GoodreadsBusinessArgues against central planning and highlights the unintended negative consequences of government intervention, sharing a philosophical skepticism of top-down solutions.
- Steve Jobs
Walter Isaacson
4.1 (957k) average on GoodreadsBusinessSteve Jobs was a visionary who fused creativity and technology to revolutionize six industries and shape our digital world.
- Freakonomics: A Rogue Economist Explores the Hidden Side of Everything
Steven D. Levitt
4.0 (709k) average on GoodreadsBusinessThis book uses economic principles to reveal the surprising incentives behind everything from drug dealing and real estate to cheating teachers and the decline of crime.
- The Tipping Point: How Little Things Can Make a Big Difference
Malcolm Gladwell
4.0 (690k) average on GoodreadsBusinessMalcolm Gladwell explains how small, targeted actions can start widespread changes in trends, behaviors, and ideas.
- Outliers: The Story of Success
Malcolm Gladwell
4.2 (556k) average on GoodreadsBusinessMalcolm Gladwell argues that true success is not just about individual talent, but about the hidden advantages of culture, opportunity, and unique experiences that shape extraordinary lives.
- The Subtle Art of Not Giving a F*ck: A Counterintuitive Approach to Living a Good Life
Mark Manson
3.9 (530k) average on GoodreadsBusinessEmbrace your flaws and stomach life's lemons, because true happiness isn't about relentless positivity, but about choosing what truly matters to give a f*ck about.



Enjoyed the summary?
A summary gives you the shape of the book. The book itself has the detail, the examples and the voice.
Find Economic Facts and Fallacies on AmazonAs an Amazon Associate, BookBrief earns from qualifying purchases. How we're funded