Core Idea
- Difficulty
- Easy
- Read it if
- You are struggling with debt, need a clear, step-by-step plan to manage your money, or want to build a solid financial foundation based on proven principles of saving and investing.
- Skip it if
- You are already debt-free, have a sophisticated investment strategy, or prefer a more nuanced economic perspective over a straightforward, faith-based financial plan.
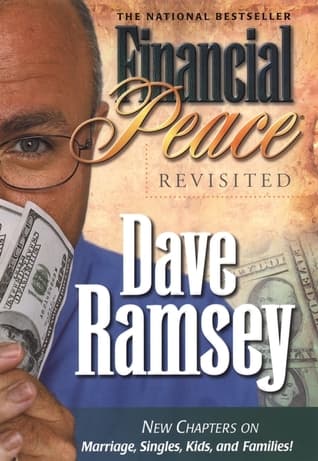
Key Takeaways from Financial Peace Revisited
The Debt Snowball: Unleash Momentum
Attack debt strategically, building psychological wins to accelerate your progress.
Ramsey says the Debt Snowball is the most effective way to become debt-free. It is not mathematically superior in minimizing interest (the avalanche method does that), but it is psychologically superior. The idea is to list all your debts from smallest balance to largest. You make minimum payments on all debts except the smallest, on which you put every extra dollar you can find. Once that smallest debt is paid off, you take the money you were paying on it (minimum payment + extra) and add it to the minimum payment of the next smallest debt. This creates a snowball effect: each paid-off debt frees up more money to attack the next, building momentum and motivation. It prioritizes quick wins and behavior change over numerical optimization, recognizing that personal finance is 80% behavior and 20% knowledge.
“The debt snowball method is where you pay off your debts in order from smallest to largest, regardless of the interest rate. Once the smallest debt is paid off, you take the money you were paying on that debt and apply it to the next smallest debt.”
In the book: Ramsey recounts countless stories from callers to his radio show and participants in his Financial Peace University classes who attest to the psychological power of the snowball. People often quit on mathematically 'optimal' plans because they lack the immediate gratification and visible progress that the snowball provides.
Try this: List all your debts (excluding your mortgage for now) from smallest balance to largest. Commit to making only minimum payments on all but the smallest. Attack that smallest debt with intense focus, cutting expenses and finding extra income. Once it's gone, roll that payment into the next debt. Celebrate each payoff to reinforce positive behavior.
Related ideas: debt-snowball, financial-peace-university, debt-elimination
Emergency Fund: Your Financial Foundation
Build a cash buffer to absorb life's inevitable shocks without resorting to debt.
Before tackling debt or investing, Ramsey insists on establishing an emergency fund. This is a foundational step in his 'Baby Steps' plan. He recommends starting with a 'starter' emergency fund of $1,000 during the debt snowball phase and then expanding it to 3-6 months of essential living expenses after all non-mortgage debt is paid off. This fund acts as a financial shock absorber, stopping unexpected expenses like car repairs, medical emergencies, or job loss from derailing your progress and forcing you back into debt. It provides peace of mind and financial stability, allowing you to handle life's curveballs without panic or credit cards.
“An emergency fund is not an investment; it is insurance. It's there to protect you from the financial storms of life.”
In the book: Ramsey frequently shares anecdotes of people whose lives were thrown into chaos by unexpected expenses, leading them back into debt cycles. He cites the statistic that most Americans can't cover a $400 emergency without selling something or going into debt, highlighting the widespread need for this buffer.
Try this: Prioritize saving $1,000 in a separate, easily accessible savings account. Once your non-mortgage debts are cleared (Baby Step 3), focus intensely on growing this fund to cover 3-6 months of your essential living expenses. Keep it liquid and untouched for true emergencies only.
Related ideas: emergency-fund, baby-steps, financial-security
The Danger of Debt: A Slave to the Lender
Understand that debt is a tool that robs you of future income and freedom.
Ramsey takes an uncompromising stance against debt. He sees it not as a necessary financial tool but as a destructive force that hinders wealth building and personal freedom. He argues that the idea of 'good debt' (like student loans or car loans) is a myth, as all debt carries risk and costs interest, effectively stealing from your future earnings. He emphasizes that debt stops you from truly owning your income, as part of every paycheck goes to past purchases. This 'slavery' to lenders restricts your options, increases stress, and diverts money that could otherwise be invested or saved for true wealth creation. His philosophy advocates for living completely debt-free (except for a mortgage, which is tackled later) to maximize financial flexibility and peace.
“The borrower is slave to the lender. Debt is not a tool; it is a monument of financial bondage.”
In the book: Ramsey frequently cites the biblical proverb, 'The rich rule over the poor, and the borrower is slave to the lender,' as a core tenet. He also shares numerous personal stories of his own bankruptcy due to excessive debt and the subsequent struggles of individuals trapped in debt cycles.
Try this: Adopt a 'no-debt' mindset. Avoid credit cards, car loans, and student loans whenever possible. If you have debt, commit to paying it off aggressively using the Debt Snowball. Before making any significant purchase, ask yourself if you can truly afford it without borrowing.
Related ideas: debt-free-living, credit-cards, financial-bondage
The KISS Rule of Investing: Keep It Simple, Stupid
Avoid complex investments and focus on long-term growth through diversified mutual funds.
Ramsey's investment philosophy is simple and focused on long-term growth. He strongly suggests investing in growth stock mutual funds with a long track record, managed by professionals. He dismisses individual stock picking, day trading, and complex investment schemes as too risky and time-consuming for the average person. His 'KISS' (Keep It Simple, Stupid) rule emphasizes diversification across four types of mutual funds (growth, growth and income, international, and aggressive growth) within tax-advantaged accounts like 401(k)s and Roth IRAs. The goal is consistent, steady growth over decades, using the power of compound interest, rather than chasing quick riches or trying to beat the market.
“Investing doesn't have to be complicated. The best investors are usually the ones who keep it simple.”
In the book: Ramsey points to the historical performance of the stock market over long periods, demonstrating that diversified mutual funds consistently outperform most individual investors and complex strategies. He often highlights the fees and risks associated with actively managed individual portfolios versus low-cost index-based mutual funds.
Try this: Once your emergency fund is fully funded and non-mortgage debt is gone, start investing 15% of your gross income. Prioritize tax-advantaged accounts (401k up to employer match, then Roth IRA, then back to 401k). Invest in good quality, diversified growth stock mutual funds across the four categories Ramsey suggests.
Related ideas: mutual-funds, compound-interest, retirement-planning, roth-ira
Contentment: The Antidote to Consumerism
Cultivate satisfaction with what you have to break free from the cycle of endless wanting.
Ramsey says consumerism and the 'keeping up with the Joneses' mentality cause much financial distress. He argues that true financial peace requires contentment. This means choosing to be satisfied with your current possessions and lifestyle, rather than always chasing the next new car, gadget, or bigger house. Contentment frees you from the pressure to spend beyond your means, reduces financial stress, and allows you to direct your money towards your long-term goals. It is a mindset shift that recognizes the true value of experiences and relationships over material possessions, leading to greater financial freedom and personal happiness.
“Contentment is not the fulfillment of what you want, but the realization of how much you already have.”
In the book: Ramsey shares personal anecdotes of how his own pursuit of wealth and material possessions ultimately led to bankruptcy and unhappiness. He often refers to the societal pressure created by advertising and social media to constantly acquire more, leading many into debt.
Try this: Practice gratitude daily. Unsubscribe from marketing emails that tempt you to spend. Avoid comparing your lifestyle to others. Before making a purchase, ask if it truly adds value to your life or if it's simply fulfilling a temporary desire fueled by external pressures.
Related ideas: consumerism, gratitude, financial-freedom, minimalism
The Power of the Budget: Giving Every Dollar a Job
Gain control over your money by intentionally planning where every dollar goes.
Ramsey considers budgeting an essential tool for financial peace. He views a budget as a liberation — a proactive plan for your money, rather than a reactive response to spending. The core principle is the 'zero-based budget,' where every dollar of your income is assigned a specific job (savings, debt payment, bills, spending) until your income minus your expenses equals zero. This intentionality eliminates financial 'leakage,' reveals wasteful spending, and ensures that your money aligns with your financial goals. It empowers you to make conscious choices about your spending, rather than letting your money simply disappear.
“A budget is telling your money where to go instead of wondering where it went.”
In the book: Ramsey frequently shares success stories from individuals and families who transformed their finances by diligently following a budget. He often uses the analogy of a business needing a budget to thrive, arguing that personal finances are no different.
Try this: Create a monthly zero-based budget. Track all your income and expenses. Assign every dollar a category until your income minus your expenses equals zero. Review and adjust your budget regularly (at least monthly) to ensure it reflects your current situation and goals.
Related ideas: zero-based-budget, financial-planning, money-management
Family and Money: A United Front
Align your financial goals with your spouse to strengthen your relationship and accelerate progress.
Ramsey says money is the leading cause of marital strife and divorce. He emphasizes that for couples, financial peace is a team sport. Both partners must be engaged, transparent, and aligned on their financial goals and spending habits. This requires open, honest communication, compromise, and a shared vision for their financial future. He advocates for joint accounts, shared budgets, and regular 'money dates' to discuss finances, make decisions together, and celebrate progress. When couples work together, their combined effort and commitment create a strong force for wealth building and a more harmonious relationship.
“Money problems are the number one cause of divorce. If you want a strong marriage, you have to get on the same page with your money.”
In the book: Ramsey frequently cites statistics on divorce rates linked to financial disagreements. He shares numerous stories from his counseling experience where couples' financial misalignment led to severe relationship stress, and conversely, how financial unity strengthened marriages.
Try this: If you're married, sit down with your spouse and create a budget together. Discuss your financial dreams and fears. Hold regular 'money dates' to review your budget, make financial decisions, and ensure you're both working towards the same goals. Be transparent about all income and spending.
Related ideas: money-and-marriage, financial-communication, relationship-goals
Giving: The Ultimate Act of Generosity
Integrate charitable giving into your financial plan as a core principle, not an afterthought.
Ramsey places importance on giving, calling it a key part of financial peace and personal fulfillment. He argues that generosity breaks the psychological hold money can have, creating a spirit of abundance rather than scarcity. By intentionally budgeting for charitable giving (often suggesting tithing 10% as a starting point), individuals show that they control their money, not the other way around. This act of giving, even on a tight budget, cultivates a grateful heart, reinforces contentment, and brings greater satisfaction than simply accumulating wealth. It is a foundational principle that goes beyond financial mechanics.
“When you give, you are breaking the power of money over you. You are saying, 'I am not controlled by this stuff.'”
In the book: Ramsey frequently references biblical principles regarding tithing and generosity. He shares countless stories from his community and listeners about the profound positive impact giving has had on their lives, often citing how 'givers gain' and experience greater personal and financial blessings.
Try this: Once your $1,000 emergency fund is saved, integrate giving into your budget. Start with a percentage you're comfortable with (Ramsey often suggests 10% as a tithe), and make it a non-negotiable line item, just like any other bill. Give to causes you believe in.
Related ideas: tithing, charitable-giving, generosity, financial-stewardship
Live Like No One Else: Sacrifice for Future Freedom
Embrace temporary sacrifice to achieve financial independence that others only dream of.
This mantra sums up Ramsey's philosophy: the willingness to make radical, often uncomfortable, financial choices now to secure an extraordinary future. It means giving up instant gratification, cutting unnecessary expenses, and working extra hours while others spend freely and accumulate debt. This period of intense focus and sacrifice – living 'lean' – is temporary. The reward is long-term financial freedom, the ability to give generously, and the peace of mind that comes from being debt-free and wealthy. It is about choosing a different path than the majority, who are often trapped in debt, to achieve a dramatically different and more fulfilling outcome.
“If you will live like no one else, later you can live like no one else.”
In the book: Ramsey uses his own story of losing everything and rebuilding through extreme discipline as a prime example. He also showcases numerous success stories from Financial Peace University graduates who committed to intense sacrifice and reaped significant rewards.
Try this: Identify areas where you can cut spending drastically. Consider taking on a side hustle or working extra hours to accelerate your debt payoff or savings. Embrace a mindset of delayed gratification and constantly remind yourself of the future freedom you are working towards.
Related ideas: financial-independence, delayed-gratification, sacrifice, wealth-building
Insurance: Protect Your Progress
Adequately insure yourself against major risks to safeguard your financial journey.
Ramsey stresses the critical role of proper insurance in protecting your financial progress. He differentiates between necessary insurance (health, term life, auto, homeowner's/renter's, long-term disability) and unnecessary or 'bad' insurance (whole life, credit card protection, extended warranties). The goal is to transfer catastrophic financial risk to an insurance company, stopping unexpected events from wiping out your savings or forcing you back into debt. He advises getting enough coverage, especially for term life insurance if you have dependents, and long-term disability to protect your income. This step ensures that while you work through the Baby Steps, you are not vulnerable to unforeseen tragedies that could derail everything.
“Insurance is not an investment; it is risk transfer. You buy it to protect your stuff and your future.”
In the book: Ramsey often shares heartbreaking stories of families devastated financially by illness, accidents, or premature death due because of insufficient or incorrect insurance coverage. He provides clear examples of how term life insurance, for instance, is a far better value than whole life for most people.
Try this: Review all your insurance policies. Ensure you have adequate health, term life (if applicable), auto, homeowner's/renter's, and long-term disability insurance. Avoid whole life insurance and other unnecessary policies. Shop around for the best rates and coverage.
Related ideas: insurance, risk-management, term-life-insurance, disability-insurance
Financial Peace Revisited Quotes
“We buy things we don't need, with money we don't have, to impress people we don't like.”
“Debt is normal. Be weird.”
“You must gain control over your money or the lack of it will forever control you.”
“Live like no one else, so later you can live like no one else.”
“A budget is telling your money where to go instead of wondering where it went.”
“Your most powerful wealth-building tool is your income. And 70% of Americans have no idea where it went.”
“The paid-in-full mortgage is the only mortgage you should ever have.”
“If you will live like no one else, later you can live like no one else.”
“Money is a tool. It's not the root of all evil. It's not the answer to all problems. It's simply a tool.”
“You can't get rich quick. You have to get rich slow.”
“An emergency fund is not a luxury; it's a necessity.”
“The borrower is slave to the lender.”
“Your greatest asset is your income, and your greatest tool is your budget.”
“The average millionaire has seven streams of income.”
“You have to walk away from the herd. You have to be willing to be different.”
Quiz
10 questions on the main ideas. Each answer comes with a short explanation.
Question 1
According to Dave Ramsey in 'Financial Peace Revisited', what is the recommended first step in his Baby Steps plan?
- Pay off all debt using the debt snowball.
- Save $1,000 for a starter emergency fund.
- Invest 15% of your household income into retirement.
- Save 3-6 months of expenses in a fully funded emergency fund.
Show answer
B. Save $1,000 for a starter emergency fund. Baby Step 1 is to save $1,000 for a starter emergency fund. This provides a buffer for unexpected expenses while you tackle debt.
Question 2
What does Dave Ramsey advocate for in the 'debt snowball' method?
- Paying off debts with the highest interest rates first.
- Paying off debts with the lowest balances first, regardless of interest rate.
- Consolidating all debts into one loan.
- Making minimum payments on all debts until one is paid off.
Show answer
B. Paying off debts with the lowest balances first, regardless of interest rate. The debt snowball method focuses on psychological wins by paying off the smallest debt first, then rolling that payment into the next smallest, building momentum.
Question 3
Which of the following is NOT one of Dave Ramsey's recommended investment types for Baby Step 4?
- Roth IRAs
- Growth stock mutual funds
- Whole life insurance as an investment
- 401(k)s with company match
Show answer
C. Whole life insurance as an investment Dave Ramsey strongly advises against using whole life insurance as an investment vehicle, preferring term life insurance for protection and investing separately.
Question 4
What is the 'KISS rule' of investing, as presented by Dave Ramsey in 'Financial Peace Revisited'?
- Keep Investment Strategies Simple and Secure.
- Know Your Investments, Stay Smart.
- Keep It Simple, Stupid.
- Key Investments Secure Success.
Show answer
C. Keep It Simple, Stupid. The KISS rule, 'Keep It Simple, Stupid,' is Ramsey's mantra for investing, advocating for straightforward mutual funds rather than complex or speculative investments.
Question 5
Dave Ramsey emphasizes the importance of a zero-based budget. What does he mean by this concept?
- A budget where you only track expenses, not income.
- A budget where your income minus your expenses equals zero, meaning every dollar is assigned a job.
- A budget that starts with zero debt.
- A budget that focuses only on paying off debt, not on spending.
Show answer
B. A budget where your income minus your expenses equals zero, meaning every dollar is assigned a job. A zero-based budget means that your income for the month minus your expenses for the month should equal zero. Every dollar is accounted for and assigned a purpose.
Question 6
According to 'Financial Peace Revisited', what role does 'contentment' play in financial decision-making?
- It means being satisfied with less, which is crucial for avoiding debt and building wealth.
- It encourages frequent self-rewards for financial milestones.
- It suggests that financial peace is achieved only when all material desires are met.
- It is a passive approach that allows others to manage your finances.
Show answer
A. It means being satisfied with less, which is crucial for avoiding debt and building wealth. Ramsey argues that contentment is a key principle to guide financial decision-making, helping individuals resist consumerism and avoid lifestyle inflation, which are common drivers of debt.
Question 7
Dave Ramsey strongly advises against co-signing loans for friends or family. What is his primary reasoning?
- It can damage your credit score even if the other person makes payments.
- It almost always results in the co-signer having to pay the debt, potentially ruining relationships and finances.
- It is illegal in many states without proper legal documentation.
- It prevents the co-signer from obtaining their own loans in the future.
Show answer
B. It almost always results in the co-signer having to pay the debt, potentially ruining relationships and finances. Ramsey emphasizes that co-signing a loan means you are 100% responsible for the debt if the primary borrower defaults, and statistics show this happens frequently, leading to financial and relational strain.
Question 8
What is Dave Ramsey's stance on using credit cards?
- He recommends using them for rewards points and paying them off in full each month.
- He advises against using them entirely, advocating for cash or debit card usage instead.
- He suggests using them only for emergencies.
- He believes they are a necessary tool for building a good credit score.
Show answer
B. He advises against using them entirely, advocating for cash or debit card usage instead. Ramsey is famously anti-credit card, arguing that they lead to debt and that a credit score is not necessary for true financial freedom. He promotes a cash-based system.
Question 9
Beyond the financial aspect, 'Financial Peace Revisited' discusses how the 'flow of money can revolutionize relationships.' What is a key argument Ramsey makes regarding finances and marriage?
- Spouses should maintain separate bank accounts for financial independence.
- One spouse should be solely responsible for managing all household finances.
- Financial discussions should be avoided to prevent conflict.
- Couples should work as a team on financial decisions, with open communication and shared goals, to strengthen their bond.
Show answer
D. Couples should work as a team on financial decisions, with open communication and shared goals, to strengthen their bond. Ramsey emphasizes that money is a major source of conflict in marriage and that couples must unite as a team, communicate openly, and make joint financial decisions to achieve financial peace and strengthen their relationship.
Question 10
Dave Ramsey's personal story, detailed in 'Financial Peace Revisited', highlights his experience of losing a significant real estate portfolio. What was his age when he lost his four-million-dollar portfolio?
- 26
- 30
- 35
- 40
Show answer
B. 30 The book's introduction states that Dave Ramsey lost his four-million-dollar real estate portfolio by age thirty, after having built it by age twenty-six.
Financial Peace Revisited FAQ
What is the core philosophy behind 'Financial Peace Revisited'?
The book's core philosophy centers on helping individuals achieve financial stability and peace by getting out of debt, building wealth through simple investing, and aligning financial decisions with personal values like contentment, drawing from Dave Ramsey's personal experience of losing and rebuilding his wealth.
Does Dave Ramsey's 'debt snowball' method really work?
Yes, the 'debt snowball' method is a key component of Ramsey's plan and has proven effective for many. It focuses on paying off debts from smallest to largest, regardless of interest rate, to build psychological momentum and keep people motivated on their debt-free journey.
What is the 'KISS rule' of investing mentioned in the book?
The 'KISS rule' stands for 'Keep It Simple, Stupid' and advocates for straightforward, long-term investing strategies. Ramsey encourages readers to avoid complex financial products and instead focus on diversified mutual funds with a proven track record, making investing accessible to everyone.
How does 'Financial Peace Revisited' differ from other personal finance books?
This book distinguishes itself by integrating financial advice with emotional and spiritual well-being, emphasizing contentment and relationship dynamics alongside practical steps like budgeting and debt elimination. It's less about maximizing returns and more about achieving holistic financial peace.
What role does contentment play in financial decision-making according to Dave Ramsey?
Contentment is presented as a guiding principle to prevent endless consumerism and debt. By fostering contentment, individuals can make financial choices based on their true needs and values rather than societal pressures, leading to greater financial freedom and less stress.
Does 'Financial Peace Revisited' offer advice for managing money within a marriage?
Absolutely, the book dedicates significant attention to how the flow of money can impact relationships. It provides guidance on improving communication, setting shared financial goals, and working together as a team to achieve financial peace as a couple, aiming to revolutionize family dynamics.
Is 'Financial Peace Revisited' suitable for someone already out of debt?
While a large portion focuses on debt elimination, the book also covers investing, wealth building, and financial legacy planning, making it relevant for those already debt-free. It offers strategies for long-term financial security and maintaining peace.
What are the first steps recommended by Dave Ramsey to achieve financial peace?
The first steps typically involve establishing an emergency fund, getting out of debt using the debt snowball, and then moving into investing for retirement. Ramsey outlines a clear, step-by-step 'Baby Steps' plan to guide readers through their financial journey.
About the author
Dave Ramsey is a nationally syndicated radio host and author. He is best known for his book 'Financial Peace Revisited,' which outlines his principles for debt-free living. Ramsey's work focuses on practical financial advice and motivational strategies for individuals seeking financial freedom.
Similar books
- Steve Jobs
Walter Isaacson
4.1 (957k) average on GoodreadsBusinessSteve Jobs was a visionary who fused creativity and technology to revolutionize six industries and shape our digital world.
- Freakonomics: A Rogue Economist Explores the Hidden Side of Everything
Steven D. Levitt
4.0 (709k) average on GoodreadsBusinessThis book uses economic principles to reveal the surprising incentives behind everything from drug dealing and real estate to cheating teachers and the decline of crime.
- The Tipping Point: How Little Things Can Make a Big Difference
Malcolm Gladwell
4.0 (690k) average on GoodreadsBusinessMalcolm Gladwell explains how small, targeted actions can start widespread changes in trends, behaviors, and ideas.
- Outliers: The Story of Success
Malcolm Gladwell
4.2 (556k) average on GoodreadsBusinessMalcolm Gladwell argues that true success is not just about individual talent, but about the hidden advantages of culture, opportunity, and unique experiences that shape extraordinary lives.
- The Subtle Art of Not Giving a F*ck: A Counterintuitive Approach to Living a Good Life
Mark Manson
3.9 (530k) average on GoodreadsBusinessEmbrace your flaws and stomach life's lemons, because true happiness isn't about relentless positivity, but about choosing what truly matters to give a f*ck about.
- The 7 Habits of Highly Effective People: Powerful Lessons in Personal Change
Stephen R. Covey
4.1 (524k) average on GoodreadsBusinessThis book presents seven habits that help people live more effective, purposeful lives.



Enjoyed the summary?
A summary gives you the shape of the book. The book itself has the detail, the examples and the voice.
Find Financial Peace Revisited on AmazonAs an Amazon Associate, BookBrief earns from qualifying purchases. How we're funded