Core Idea
- Difficulty
- Medium
- Read it if
- You want a detailed, character-driven narrative explaining the specific financial products (CDOs, CDSs) and the human decisions that led to the 2008 financial crisis. You are interested in how financial innovation can spiral into systemic risk.
- Skip it if
- You are looking for a high-level overview without getting into the technical specifics of financial instruments, or prefer a purely economic analysis over a journalistic, narrative approach.
Key Takeaways from Fool's Gold
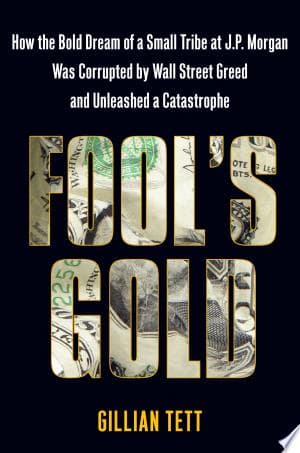
The Genesis of Financial Alchemy
How a poolside brainstorm birthed credit derivatives and revolutionized banking.
The 2008 financial crisis did not appear suddenly; its origins go back to the early 1990s and a specific moment at J.P. Morgan. A small group of bankers, later called the 'Morgan Mafia,' thought of credit derivatives during a strategic meeting. Their initial aim was to manage risk better by moving specific credit exposures off their balance sheet. This innovation allowed banks to separate and trade credit risk from the underlying loan, promising more liquidity and flexibility. Tett points out how this idea, meant for better risk management, accidentally set the stage for a financial revolution that would eventually get out of control. It changed how risk was viewed and transferred in the financial system, moving away from traditional loan creation and holding.
“The story begins with the intense Morgan brainstorming session in 1994 beside a pool in Boca Raton, where the team cooked up a dazzling new idea for the exotic financial product known as credit derivatives.”
In the book: The 1994 Boca Raton brainstorming session at J.P. Morgan where the concept of credit derivatives was first formulated by a small team seeking to manage the bank's exposure to a specific loan to Exxon.
Try this: Understand how seemingly positive financial innovations, born from rational needs, can have unforeseen and destabilizing long-term consequences if not properly understood and regulated.
Related ideas: credit-derivatives, financial-innovation, risk-management
The Unbundling of Risk
Credit derivatives allowed banks to dissect and trade risk, fundamentally changing financial architecture.
The main innovation of credit derivatives was the ability to 'unbundle' risk. Instead of a bank holding a loan and all its risks until maturity, credit derivatives allowed them to sell the credit risk component to another party. This meant a bank could create a loan, package its credit risk into a Credit Default Swap (CDS) or Collateralized Debt Obligation (CDO), and sell it, effectively removing that risk from its balance sheet. This created an illusion of lower risk for the originating bank, freeing up capital and encouraging more lending. Tett emphasizes how attractive this mechanism became, leading to a huge expansion of credit and a 'turbocharged derivatives trade.' The problem, however, was that risk was transferred, not eliminated, and its new location often became unclear, creating a complex network of linked liabilities.
“That idea would rip around the banking world, catapult Morgan to the top of the turbocharged derivatives trade, and fuel an extraordinary banking boom that seemed to have unleashed banks from ages-old constraints of risk.”
In the book: The rapid growth of the credit derivatives market from a niche product to a multi-trillion-dollar industry, and J.P. Morgan's initial dominance in this market due to their pioneering efforts.
Try this: When evaluating complex financial instruments, always question where the risk truly goes and whether its new location is transparent and well-understood by all parties.
Related ideas: credit-default-swap, collateralized-debt-obligation, risk-transfer
The Illusion of Risk Mitigation
Derivatives promised safer banking but created a 'shadow banking' world of hidden dangers.
While credit derivatives were initially designed to reduce risk for individual institutions, their widespread use and later misuse created systemic weaknesses. Tett shows how the ability to offload risk led to complacency and encouraged greater leverage across the financial system. Many of these complex derivatives were traded 'over-the-counter' (OTC), outside traditional exchanges and without central clearing. This lack of transparency and regulation allowed a 'shadow banking' world to grow, where large amounts of risk accumulated mostly unseen. The promise of distributing risk widely meant that when the housing market collapsed, the connections between these unclear instruments ensured that contagion spread quickly and unpredictably, surprising regulators and many bankers.
“The deeply reported and lively narrative takes readers behind the scenes, to the inner sanctums of elite finance and to the secretive reaches of what came to be known as the 'shadow banking' world.”
In the book: The proliferation of OTC derivatives and the expansion of entities like Structured Investment Vehicles (SIVs) that operated largely outside traditional banking regulations, holding vast amounts of securitized assets.
Try this: Be wary of solutions that promise to eliminate risk entirely; often, they merely transform and relocate it, potentially making it harder to track and manage.
Related ideas: shadow-banking, over-the-counter, systemic-risk
Hubris, Delusion, and Greed
The moral decay of the banking world led to the perversion of financial innovation.
Tett directly attributes blame for the crisis to the 'hubris, delusion, and sheer greed' that affected major banking institutions beyond J.P. Morgan. While the initial idea of credit derivatives made sense, other banks took the concept to dangerous extremes, creating increasingly complex and ultimately toxic products like CDOs of CDOs, often backed by subprime mortgages. The pursuit of short-term profits, driven by large bonuses linked to deal volume rather than long-term risk assessment, overshadowed any real concern for systemic stability. This moral failure led these institutions to ignore clear warning signs and to create financial instruments that even their creators struggled to understand, let alone accurately price for risk. It was a classic case of good intentions leading to financial disaster.
“But when the Morgan team’s derivatives dream collided with the housing boom, and was perverted—through hubris, delusion, and sheer greed—by titans of banking that included Citigroup, UBS, Deutsche Bank, and the thundering herd at Merrill Lynch—even as J.P. Morgan itself stayed well away from the risky concoctions others were peddling—catastrophe followed.”
In the book: The aggressive marketing and sale of subprime mortgage-backed securities and complex CDOs by banks like Merrill Lynch and Citigroup, despite internal warnings and deteriorating underlying asset quality.
Try this: Recognize that technological or financial innovation, no matter how brilliant, can be corrupted by human factors like unchecked greed and a failure of ethical leadership. Always scrutinize incentives.
Related ideas: moral-hazard, subprime-mortgage, banking-ethics
J.P. Morgan's Prudent Escape
How one bank avoided the worst excesses through internal caution and skepticism.
A key part of Tett's story is the clear difference between J.P. Morgan's approach and that of its competitors. Despite being the innovators of credit derivatives, J.P. Morgan largely avoided the riskiest, most complex creations that fueled the bubble. Under Jamie Dimon's leadership, the bank remained somewhat skeptical about the growing market, especially concerning subprime mortgage-backed assets. They understood the complexities of the products they created and, importantly, understood their limits and potential for misuse. This internal caution, combined with a willingness to question common market sentiment, allowed them to sell off many risky positions and avoid the huge losses that crippled other institutions. Their story shows the importance of conservative risk management and a culture that valued prudence over unchecked growth.
“Tett’s access to Dimon and the J.P. Morgan leaders who so skillfully steered their bank away from the wild excesses of others sheds invaluable light not only on the untold story of how they engineered their bank’s escape from carnage but also on how possible it was for the larger banking world, regulators, and rating agencies to have spotted, and heeded, the terrible risks of a meltdown.”
In the book: J.P. Morgan's early exit from the riskiest tranches of the CDO market and their decision to hold onto fewer subprime-related assets compared to competitors, often selling them off to other banks.
Try this: Cultivate a culture of skepticism and independent analysis, even when faced with widespread market enthusiasm. Prioritize genuine risk assessment over chasing short-term profits.
Related ideas: risk-aversion, conservative-banking, corporate-culture
The Blinders of Specialization
Over-specialization created silos that prevented a holistic view of systemic risk.
Tett argues that a major factor in the collective blindness was the extreme specialization within financial institutions and regulatory bodies. Bankers became experts in narrow areas — whether mortgage origination, securitization, or derivatives trading — often without a full understanding of how these parts connected. Regulators were similarly isolated, with different agencies overseeing different aspects of the financial system, but no single entity had a complete view of the accumulating systemic risk. This 'silo mentality' meant that while individual parts of the system might have seemed sound, the complex network of dependencies and exposures went largely unmonitored and misunderstood. The right hand did not know, or could not grasp, what the left hand was doing, leading to a fragmented and ultimately disastrous oversight failure.
“The story...sheds invaluable light not only on the untold story of how they engineered their bank’s escape from carnage but also on how possible it was for the larger banking world, regulators, and rating agencies to have spotted, and heeded, the terrible risks of a meltdown.”
In the book: The disconnect between mortgage originators, who often didn't care about loan quality, and the derivative traders, who relied on the performance of those mortgages, and the various regulatory bodies with overlapping but incomplete jurisdictions.
Try this: Foster interdisciplinary collaboration and communication within organizations to break down silos. Encourage a 'big picture' perspective that connects specialized knowledge to the broader context.
Related ideas: silo-mentality, regulatory-failure, systemic-interconnectedness
The Rating Agencies' Role
Flawed models and conflicts of interest rendered rating agencies useless, or worse.
The failure of credit rating agencies like Moody's and S&P is a clear problem highlighted by Tett. These agencies, meant to be independent evaluators of risk, regularly gave AAA ratings to highly complex and ultimately toxic mortgage-backed securities and CDOs. Their models were often insufficient, failing to account for correlated defaults in a nationwide housing downturn. More critically, a fundamental conflict of interest existed: the rating agencies were paid by the very institutions whose products they were rating. This encouraged loose standards and a race to the bottom, as banks would seek the most favorable ratings. This created a false sense of security for investors and regulators, who relied on these 'gold standard' ratings, allowing the market for these dangerous instruments to grow unchecked.
“how possible it was for the larger banking world, regulators, and rating agencies to have spotted, and heeded, the terrible risks of a meltdown.”
In the book: The widespread AAA ratings given to subprime mortgage-backed securities and CDOs that quickly collapsed in value during the crisis, and the subsequent investigations into the rating agencies' practices.
Try this: Do not blindly trust 'independent' assessments without understanding their underlying methodologies and potential conflicts of interest. Always perform your own due diligence.
Related ideas: credit-rating-agencies, conflict-of-interest, regulatory-oversight
The Dangers of Financial Abstraction
As finance grew more abstract, its connection to real-world assets faded, increasing risk.
Tett implies that the increasing abstraction of finance played a significant role in the crisis. Credit derivatives, and especially CDOs, were several steps removed from the underlying assets — individual mortgages. As these products became more complex and were repackaged multiple times, their connection to the real-world performance of those mortgages became weak and hard to trace. This abstraction allowed bankers to trade 'risk' as a theoretical commodity, often losing sight of the actual homes, families, and economic realities it represented. When the housing market declined, this disconnect meant that the true scale of the problem was hidden until it was too late. The 'brilliance' of financial engineering ultimately led to 'blind ambition' because the human element and real-world consequences were removed from consideration.
“A tale of blistering brilliance and willfully blind ambition, Fool’s Gold is both a rare journey deep inside the arcane and wildly competitive world of high finance and a vital contribution to understanding how the worst economic crisis since the Great Depression was perpetrated.”
In the book: The creation of synthetic CDOs that didn't even rely on actual mortgages but derived their value from the performance of other credit derivatives, further distancing them from tangible assets.
Try this: Always strive to understand the underlying real-world assets and economic fundamentals behind any financial instrument, no matter how complex or abstract its structure.
Related ideas: financial-abstraction, asset-backed-securities, real-economy
The Peril of Unseen Interconnections
The crisis revealed a deeply interconnected financial system where failure spread like wildfire.
One of Tett's most important contributions is showing the deep interconnectedness of the modern financial system, particularly through derivatives. The initial failure in the subprime mortgage market did not stay contained; it spread quickly through the network of CDOs and CDSs, affecting institutions globally. Banks were exposed to each other's failures through these instruments in ways that were largely invisible and poorly understood before the crisis. The 'shadow banking' system, in particular, created vast, unclear linkages that amplified contagion. The fall of Lehman Brothers, for instance, sent shockwaves through the entire system not just because of its direct counterparties, but because its failure triggered a cascade of obligations and doubts about the solvency of countless other institutions. The crisis was less about isolated failures and more about the systemic risk built into an over-leveraged and untransparent network.
“The story...sheds invaluable light not only on the untold story of how they engineered their bank’s escape from carnage but also on how possible it was for the larger banking world, regulators, and rating agencies to have spotted, and heeded, the terrible risks of a meltdown.”
In the book: The rapid spread of losses from subprime mortgages to major global banks through complex derivatives, leading to a liquidity crisis and the freezing of interbank lending markets.
Try this: When assessing risk, consider not just direct exposures but also indirect, systemic interconnections. Assume that failures in one area can rapidly cascade through complex systems.
Related ideas: financial-contagion, interconnectedness, systemic-risk-management
Fool's Gold Quotes
“The price of anything is what someone else is prepared to pay for it.”
“When you have a situation where banks are lending to each other but don't really understand what's on each other's balance sheets, that's a recipe for disaster.”
“The very tools designed to reduce risk can, in aggregate, create new and larger risks.”
“Sometimes, the most important things are the ones you can't see.”
“The problem with models is that they are only as good as the assumptions built into them.”
“It was a failure of imagination, a failure to think about what could go wrong outside the established frameworks.”
“The financial system had become a giant, interconnected web, where a problem in one corner could quickly unravel the whole thing.”
“In the world of finance, 'innovation' can often be a euphemism for 'complexity' and 'opacity'.”
“The incentive structures in place often rewarded short-term gains over long-term stability.”
“Regulators were often fighting the last war, not the one that was actually unfolding.”
“Culture eats strategy for breakfast, and in finance, the culture of deal-making often overshadowed risk management.”
“The story of modern finance is, in many ways, a story of categories – how we define them, how we group them, and how we sometimes ignore them.”
“When everyone is doing the same thing, the risk is not diversified; it's concentrated.”
“The most dangerous phrase in the English language is 'We've always done it this way.'”
Quiz
10 questions on the main ideas. Each answer comes with a short explanation.
Question 1
Which financial product, conceived by J.P. Morgan in Boca Raton in 1994, is identified by Gillian Tett as a key catalyst for the banking revolution that escalated out of control?
- Mortgage-Backed Securities (MBS)
- Collateralized Debt Obligations (CDOs)
- Credit Default Swaps (CDS)
- Credit derivatives
Show answer
D. Credit derivatives The book explicitly states that the J.P. Morgan team 'cooked up a dazzling new idea for the exotic financial product known as credit derivatives' in Boca Raton in 1994, which then 'rip around the banking world'.
Question 2
Which J.P. Morgan CEO provided Gillian Tett with exclusive access for 'Fool's Gold'?
- Lloyd Blankfein
- Jamie Dimon
- Richard Fuld
- John Stumpf
Show answer
B. Jamie Dimon The text explicitly mentions 'Drawing on exclusive access to J.P. Morgan CEO Jamie Dimon'.
Question 3
According to Tett, what was the primary reason J.P. Morgan managed to 'steer their bank away from the wild excesses of others' during the lead-up to the 2008 crisis?
- Strict government regulation imposed on J.P. Morgan
- Their bank's smaller size compared to competitors
- The Morgan team's skillful navigation and avoidance of the risky concoctions others were peddling
- A sudden market downturn that forced them to divest risky assets
Show answer
C. The Morgan team's skillful navigation and avoidance of the risky concoctions others were peddling The book states 'J.P. Morgan itself stayed well away from the risky concoctions others were peddling' and highlights 'how they engineered their bank’s escape from carnage'.
Question 4
The 'Morgan Mafia' refers to what specific group within J.P. Morgan?
- A group of compliance officers enforcing strict internal rules.
- A tightly bonded team of bankers responsible for innovation.
- The board of directors overseeing strategic decisions.
- A lobbying group influencing financial policy.
Show answer
B. A tightly bonded team of bankers responsible for innovation. The description states 'a tightly bonded team of bankers known on Wall Street as the “Morgan Mafia,”' indicating their role in the bank's operations, particularly innovation.
Question 5
What key underlying factor, alongside the derivatives dream, contributed to the escalation of the banking revolution 'wildly out of control'?
- The dot-com bubble burst
- The rise of international trade agreements
- The housing boom
- Increased oil prices
Show answer
C. The housing boom The text states: 'But when the Morgan team’s derivatives dream collided with the housing boom, and was perverted... catastrophe followed.'
Question 6
Besides J.P. Morgan, which other major banking institutions are specifically mentioned as having contributed to the perversion of the derivatives dream through 'hubris, delusion, and sheer greed'?
- Goldman Sachs, Bank of America, HSBC
- Citigroup, UBS, Deutsche Bank, Merrill Lynch
- Barclays, Credit Suisse, Wells Fargo
- Morgan Stanley, Lehman Brothers, AIG
Show answer
B. Citigroup, UBS, Deutsche Bank, Merrill Lynch The book explicitly lists 'Citigroup, UBS, Deutsche Bank, and the thundering herd at Merrill Lynch' as titans of banking that perverted the derivatives dream.
Question 7
Gillian Tett's warnings of a crisis 'more than a year ahead of the curve' primarily focused on which aspect of the financial system?
- The overvaluation of technology stocks
- The emerging market debt crisis
- The risks associated with exotic financial products like credit derivatives and the shadow banking world
- Inflationary pressures in the global economy
Show answer
C. The risks associated with exotic financial products like credit derivatives and the shadow banking world The core of the book and Tett's early warnings revolved around the 'dazzling new idea for the exotic financial product known as credit derivatives' and the 'secretive reaches of what came to be known as the 'shadow banking' world'.
Question 8
The book argues that the larger banking world, regulators, and rating agencies could have 'spotted, and heeded, the terrible risks of a meltdown'. What does this suggest about the nature of the crisis, according to Tett?
- The crisis was an unavoidable natural economic cycle.
- The risks were inherently unpredictable and emergent.
- There was a collective failure of oversight and recognition of clear warning signs.
- Only J.P. Morgan possessed the intelligence to understand the risks.
Show answer
C. There was a collective failure of oversight and recognition of clear warning signs. The statement 'how possible it was for the larger banking world, regulators, and rating agencies to have spotted, and heeded, the terrible risks' directly implies a failure of collective foresight and oversight, rather than unavoidable circumstances.
Question 9
What is the central tension or paradox explored in 'Fool's Gold' regarding the origin of credit derivatives?
- They were initially designed to reduce risk but ultimately amplified it when misused.
- They were created by government mandate but resisted by banks.
- They were intended for small businesses but only utilized by large corporations.
- They were developed in the US but only caused problems in Europe.
Show answer
A. They were initially designed to reduce risk but ultimately amplified it when misused. The initial 'bold ideas for a whole new kind of financial alchemy' and the 'derivatives dream' suggest an original intent, but it was 'perverted—through hubris, delusion, and sheer greed—by titans of banking' leading to catastrophe. This highlights the paradox of a tool that could manage risk becoming a source of systemic risk.
Question 10
The book's title, 'Fool's Gold,' most likely symbolizes what aspect of the financial innovations it describes?
- The genuine value of gold as a safe-haven asset during crises.
- The deceptive appearance of immense wealth and security offered by complex financial products that ultimately proved worthless or dangerous.
- The literal investment in gold by many financial institutions.
- The foolishness of not investing in tangible assets.
Show answer
B. The deceptive appearance of immense wealth and security offered by complex financial products that ultimately proved worthless or dangerous. Fool's Gold (pyrite) looks like gold but has no real value. This metaphor perfectly fits the description of 'dazzling new idea' and 'extraordinary banking boom' that seemed to unleash banks from 'ages-old constraints of risk,' but ultimately led to catastrophe when its true, dangerous nature was revealed.
Fool's Gold FAQ
What is 'Fool's Gold' by Gillian Tett about?
'Fool's Gold' tells the inside story of the 2008 financial crisis, focusing on the role of J.P. Morgan and the invention of credit derivatives. It explores how these financial innovations, initially brilliant, were perverted by other banks, leading to the global meltdown.
Does 'Fool's Gold' explain the origins of the 2008 financial crisis?
Yes, the book delves into the very origins of the crisis, tracing it back to a J.P. Morgan brainstorming session in 1994 where the idea for credit derivatives was first conceived. It shows how this innovation subsequently spiraled out of control.
What is a credit derivative, as explained in 'Fool's Gold'?
A credit derivative is an exotic financial product designed to transfer credit risk between parties. 'Fool's Gold' illustrates how this innovative concept, initially created by J.P. Morgan, was intended to manage risk but ultimately contributed to the crisis when misused and misunderstood.
How did J.P. Morgan avoid the worst of the 2008 meltdown, according to the book?
The book highlights how J.P. Morgan, under the leadership of Jamie Dimon, skillfully steered clear of the riskiest concoctions that other banks were peddling. It details their cautious approach and internal controls that helped them escape the severe carnage experienced by others.
How is 'Fool's Gold' different from other books about the 2008 financial crisis?
'Fool's Gold' distinguishes itself by offering exclusive access to J.P. Morgan's CEO Jamie Dimon and a tightly bonded team of bankers, providing an untold, deep-dive narrative into the creation and perversion of credit derivatives and J.P. Morgan's unique position.
Does 'Fool's Gold' expose the 'shadow banking' world?
Yes, the narrative takes readers behind the scenes into the secretive reaches of what came to be known as the 'shadow banking' world. It sheds light on how this less regulated sector played a significant role in the escalation of financial risk.
What role did hubris and greed play in the financial crisis, according to the book?
The book argues that while the initial financial innovations were brilliant, they were ultimately perverted by hubris, delusion, and sheer greed from titans of banking. This human element of ambition and short-sightedness is presented as a key factor in the catastrophe.
Could regulators and rating agencies have prevented the crisis, based on 'Fool's Gold'?
'Fool's Gold' suggests that it was indeed possible for the larger banking world, regulators, and rating agencies to have spotted and heeded the terrible risks of a meltdown. It implicitly critiques their oversight and understanding of the evolving financial landscape.
Is 'Fool's Gold' suitable for readers without a finance background?
While it delves into complex financial instruments, Gillian Tett's gripping narrative and detailed storytelling make the intricate world of high finance accessible. She brings to life the key players and events, making it understandable for a broader audience interested in the crisis.
About the author

Gillian Romaine Tett is a British author and journalist. She is the chair of the editorial board and editor-at-large, US of the Financial Times. She writes weekly columns, covering a range of economic, financial, political and social issues and co-founded Moral Money, the FT sustainability newsletter. She has written about the financial instruments that were part of the cause of the financial crisis that started in the fourth quarter of 2007, such as CDOs, credit default swaps, SIVs, conduits, and SPVs. She became renowned for her early warning that a financial crisis was looming. In February 2023, her election was announced as the next Provost of King's College, Cambridge. She is to take up the post in October 2023 in succession to Professor Michael Proctor. She will continue writing for the Financial Times.
Similar books
- The Diary of a Young Girl
Anne Frank
4.2 (2.7M) average on GoodreadsBiographyDuring the Nazi occupation, a teenage girl's diary, written from a secret annex, shares observations on humanity, hope, and the wait for freedom.
- Twisted 1. Twisted love
Ana Huang
3.7 (1.7M) average on GoodreadsA quiet billionaire with a difficult past finds his guarded heart opening to the woman he must protect, but their growing passion uncovers dangerous secrets and a shared, traumatic history.
- Eat, Pray, Love
Elizabeth Gilbert
3.6 (1.5M) average on GoodreadsLifestyleA heartbroken writer leaves her conventional life for a year-long global search for pleasure in Italy, spiritual devotion in India, and unexpected love and balance in Bali.
- Night
Elie Wiesel
4.3 (970k) average on GoodreadsBiographyIn the darkness of Auschwitz and Buchenwald, a teenage Elie Wiesel faces the extermination of his family, the loss of his faith, and the lasting scars of humanity's deepest cruelty.
- Steve Jobs
Walter Isaacson
4.1 (957k) average on GoodreadsBusinessSteve Jobs was a visionary who fused creativity and technology to revolutionize six industries and shape our digital world.
- The Glass Castle
Jeannette Walls
4.3 (903k) average on GoodreadsBiographyJeannette Walls's memoir describes her unusual childhood with brilliant, free-spirited parents whose poverty-stricken life shaped her independence and love despite family problems.

Enjoyed the summary?
A summary gives you the shape of the book. The book itself has the detail, the examples and the voice.
Find Fool's Gold on AmazonAs an Amazon Associate, BookBrief earns from qualifying purchases. How we're funded